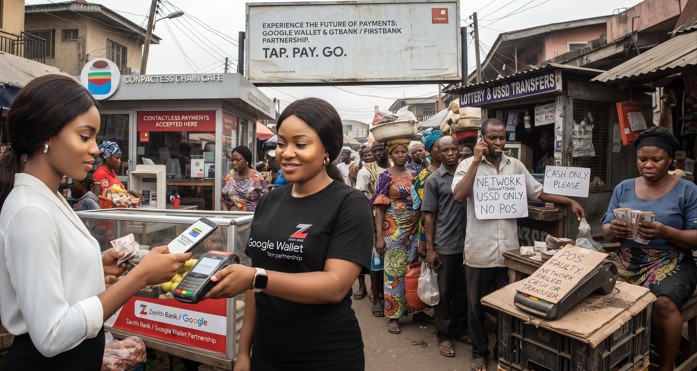
The official entry of Google Wallet into the payment ecosystem, enabling Android and Wear OS users to make tap-to-pay transactions through Near Field Communication (NFC) technology, was widely celebrated as a milestone for modern financial integration. By partnering with tier-one banks, including FirstBank, GTBank, Zenith Bank, and UBA, the global tech giant positioned its digital wallet as a frictionless alternative to physical bank cards and cash for daily commercial transactions. Yet, beneath the polished media launches and promises of contactless convenience lies a stark macroeconomic reality. In an economy where physical point-of-sale (POS) terminal failure rates remain high, and millions of citizens survive within an offline informal market, rolling out tap-to-pay infrastructure reveals a growing structural rift between global consumer technology and the daily operational limits of local commerce.
The core policy conflict sitting at the centre of this expansion is the persistent gap between consumer-facing digital innovation and back-end transaction reliability. While global technology firms and tier-one commercial banks market contactless payments as a seamless upgrade, the underlying financial rail system remains vulnerable to severe network latency, frequent interbank switching downtime, and high transaction failure rates. Deploying near-field communication protocols on top of fragile cellular connectivity and congested payment switches does not resolve the foundational bottlenecks that plague retail transactions. Instead, this push risks deepening a two-tiered financial landscape: an affluent urban minority enjoying frictionless contactless payments in high-end supermarkets and corporate chains, alongside an overwhelming majority of informal traders, rural commuters, and micro-entrepreneurs who remain bound to physical cash or basic Unstructured Supplementary Service Data (USSD) transfers out of sheer operational survival.
Global payment platforms face formidable structural headwinds when attempting to scale within the domestic retail ecosystem. Primary among these constraints is the severe hardware deficit across the merchant acquiring network. The vast majority of point-of-sale terminals deployed across the country are legacy chip-and-PIN devices that lack the hardware modules needed to execute contactless near-field communication transactions. Replacing this legacy hardware requires substantial capital expenditure from merchant acquiring banks and payment service providers, at a time when import tariffs and foreign exchange adjustments have driven up terminal procurement costs.
Furthermore, terminal acquiring fees and processing charges continue to compress merchant margins. Small and medium-sized enterprises operating on thin markups actively resist adopting specialised terminals that carry higher acquiring fees or mandatory software maintenance subscriptions. This hardware bottleneck is compounded by persistent network latency. Unlike traditional card transactions where a user bears a brief processing delay to input a Personal Identification Number (PIN), the value proposition of tap-to-pay rests on instantaneous execution at the checkout counter. When real-time switching infrastructure experiences signal latency, database timeouts, or delayed credit notifications, contactless payment stalls. Merchants, fearful of uncredited debits and prolonged chargeback resolution procedures, frequently demand that customers fall back on traditional chip-and-PIN entry or direct bank transfers, effectively neutralising the speed advantage of the technology.
This structural friction extends directly into the socio-economic domain, raising urgent questions about financial equity. The expansion of tap-to-pay technology risks widening the digital divide rather than promoting genuine financial inclusion. While payment processing applications have achieved high penetration among mobile device owners, the specific hardware requirements for mobile tap-to-pay create an immediate threshold. NFC controller chips remain predominantly restricted to mid-range and premium flagship smartphones. The broad base of the population relies on entry-level, low-cost mobile devices that lack near-field communication hardware.
As financial institutions and payment processors direct capital, technical support, and marketing resources toward optimising contactless infrastructure for high-income urban corridors, the unbanked and underbanked informal sectors are left behind. Market women, agrarian hauliers, street vendors, and informal transport operators cannot absorb the cost of NFC-enabled merchant terminals or high-end smartphones. When state monetary policies push aggressively for a cashless society without subsidising low-cost hardware or fixing basic network infrastructure, informal market participants are effectively penalised. Rather than bringing the unbanked into the formal financial fold, hyper-modern payment rails consolidate premium services within affluent urban centres, leaving rural and informal economies isolated from the primary digital economy.
The proliferation of contactless payments introduces novel security vulnerabilities and operational risks that demand a comprehensive overhaul of national cybersecurity frameworks. Traditional card-present transactions rely on two-factor authentication via a physical card and a secret PIN. Contactless payments deliberately bypass PIN entry for transactions under regulatory threshold limits to maximise transaction speed. This operational tweak alters the threat model for consumer financial security. Malicious actors equipped with portable, rogue reader devices can exploit near-field communication proximity, executing unauthorised skimming attacks in crowded public spaces like bus terminals, open-air markets, and mass transit corridors.
Equally problematic is the heightened risk of physical device theft. If a smartphone featuring an active, tokenised digital wallet falls into the hands of unauthorised parties, fraudulent micro-transactions can be swept across multiple retail points before the legitimate owner can contact their bank to block the underlying tokenised cards. On the institutional side, the regulatory frameworks governed by the Central Bank of Nigeria must move beyond establishing transaction limits to mandating zero-liability protections for victims of unauthorised contactless skimming. Payment service providers and card schemes must be legally required to deploy real-time, artificial intelligence-driven fraud detection systems capable of identifying anomalous, rapid-fire contactless transactions without shifting the burden of proof onto vulnerable consumers. Furthermore, tokenisation protocols, where actual card numbers are replaced with encrypted surrogate values, must be enforced uniformly across all participating financial institutions, ensuring that even if a transaction signal is intercepted over local wireless channels, underlying banking credentials remain completely uncompromised.
The entry of global payment platforms into the domestic market represents a notable milestone in technical integration, but software solutions alone cannot bypass basic physical infrastructure deficits. Contactless payments cannot substitute for reliable telecommunications networks, affordable hardware, and equitable financial access. Until regulatory bodies and private market actors collaborate to lower terminal procurement costs, resolve interbank network latency, and extend baseline digital access to the informal economy, tap-to-pay will remain a high-tech novelty for the urban elite rather than a transformative engine for national financial inclusion.