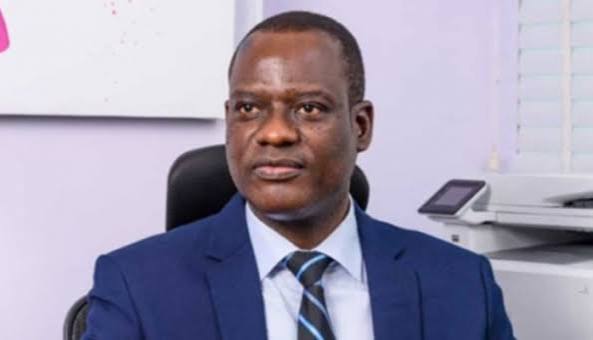
Finance Minister Taiwo Oyedele has warned that merely considering a return to petrol subsidy could push the naira to between N3,000 and N4,000 per dollar, triggering capital flight and worsening the cost-of-living crisis. He spoke at a press briefing after the IMF and World Bank annual meetings in Bangkok, where he said financial markets had already priced in policy continuity and viewed the opposition as unserious on economic management.
Oyedele’s projection is a downside scenario, not a certainty. The naira traded at N1,333.72 per dollar on the official market on October 19, with the parallel rate at N1,375, according to Central Bank of Nigeria data. Gross external reserves stood at $55.09 billion. The gap between current rates and the minister’s warning is more than N2,500, which underscores how far the currency would have to fall.
The minister’s argument rests on investor confidence. He said any signal that the administration was reconsidering subsidy would prompt foreign investors to withdraw capital while encouraging wealthy Nigerians and business owners to move savings into dollars. That would increase demand for foreign exchange, put further pressure on the naira and raise import costs, feeding into inflation. “If, for any reason, the President were to say we are merely considering the return of fuel subsidy, capital would react immediately,” he said. The very fuel people want subsidised, he added, would become more expensive in naira terms.
The debate is not abstract. Petrol prices have moved from about N238 per litre before the May 2023 subsidy removal to between N1,299 and N1,420 per litre at NNPC retail outlets in October, depending on location and payment method. The naira was trading at roughly N460 to the dollar when the subsidy ended. The twin reforms of subsidy removal and exchange-rate unification produced an almost 300 per cent increase in fuel prices within months.
Against that backdrop, the African Democratic Congress and its presidential candidate, Atiku Abubakar, have proposed a production subsidy: supplying crude to domestic refiners at a preferential price, capped and budgeted, with the benefit expected to pass through to consumers. The Presidency has rejected the plan, with spokesman Sunday Dare describing it as “economic illiteracy” and arguing that Nigeria has fewer than 700,000 barrels per day of unencumbered crude available for discretionary allocation after joint-venture obligations, royalties and profit-oil shares. Atiku has countered that President Tinubu copied the idea but reduced it to a 30-day discount, saying the government “stripped away the part that makes it work.”
Oyedele’s warning must also be read alongside the government’s own interventions. NNPC Retail has run a discount programme, and the government has discussed an ex-gantry price ceiling of N1,350 per litre. Oyedele insists these are commercial or structural measures, not subsidies. But the distinction matters less to households facing N1,400 pump prices than to markets watching for policy consistency.
The economic data offers a mixed picture. GDP grew 4.43 per cent year-on-year in the second quarter of 2026, the strongest quarterly expansion in five years, driven by agriculture, telecommunications and a rebound in oil. Yet electricity and gas contracted by 10.63 per cent, and the growth has not translated into broad relief at the household level.
For now, the naira’s stability rests on reserves, oil prices and the credibility of the reform programme. Oyedele’s N4,000 warning is a worst-case scenario, not a forecast. But it captures the core of the argument: in an economy where fuel and exchange rates move together, the cost of reversing course may be higher than the cost of staying the course.