
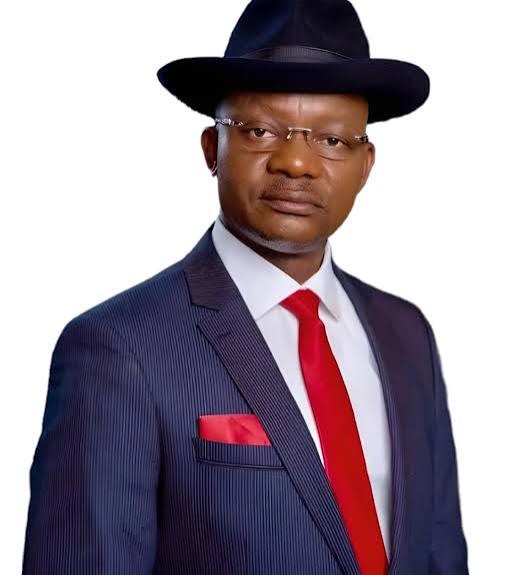
Delta Commissioner Charles Aniagwu says President Tinubu’s economic reforms are improving stability but acknowledges that rising prices continue to place significant pressure on Nigerian households.
Delta State Commissioner for Works and Public Information Charles Aniagwu has said President Bola Tinubu’s economic reforms are gradually stabilising Nigeria’s economy and could eventually improve purchasing power. Aniagwu acknowledged that the policies had increased pressure on households through higher prices, but argued that their long-term objective was to correct structural problems and place the economy on a more sustainable path. He urged Nigerians to assess the reforms beyond their immediate effects, saying the country had experienced years of fiscal pressure, inadequate revenue, foreign exchange difficulties and weak productive capacity.
Aniagwu compared the reform process to treating an open wound with iodine, explaining that the initial discomfort could be part of a longer healing process. “When you sustain an injury, there is a tendency that you are going to experience some pain. Again, when you apply iodine to treat such an open wound, it tends to cause further discomfort, but after some time, the injury begins to heal,” he said. He also illustrated his argument by comparing the reforms to choosing between two vehicles heading in different directions.
According to him, passengers might prefer a luxury vehicle because it offers greater comfort, but a less comfortable vehicle would be the better choice if it was travelling towards their intended destination. Aniagwu said the Tinubu administration had chosen to implement difficult policies to address underlying weaknesses in the economy, despite the discomfort experienced by Nigerians. He maintained that the government’s attention was gradually moving from broad economic stabilisation to interventions capable of affecting conditions at the household and community levels.
The commissioner’s comments came amid assessments of Nigeria’s economy by the International Monetary Fund and the World Bank. According to the report, the IMF said reforms introduced during the past three years had strengthened Nigeria’s macroeconomic performance and resilience. It also noted that poverty and food insecurity remained serious concerns. The World Bank similarly reported progress in restoring macroeconomic stability, citing easing inflation, stronger fiscal and external positions and resilient economic growth.
However, the institution observed that household incomes had not fully recovered despite the improvement in some economic indicators. Aniagwu said a more stable economy would strengthen the ability of federal and state governments to meet obligations such as salaries, pensions and payments to contractors.
He argued that timely payments would circulate money through different parts of the economy, benefiting schools, shops, transport operators, landlords, farmers, traders and other businesses. The commissioner said government spending on infrastructure could have a similar effect because contractors would buy materials, employ workers and patronise other enterprises. “Once the purchasing power is enhanced, people make more demands. When they make more demands, farmers can afford to grow more,” he said.
Aniagwu also pointed to intervention programmes for small businesses and vulnerable Nigerians as part of attempts to extend the effects of economic stabilisation to households. He called on the Federal Government and state administrations to continue introducing measures that would expand productive capacity, assist small businesses and enable more Nigerians to participate in economic activities.
According to him, improving production and supporting enterprises would be important to ensuring that better economic indicators eventually translate into improved living conditions. Aniagwu described economic reform as a gradual process and cautioned that the expected transformation could not occur immediately.
He said the ultimate goal should be an economy in which fiscal stability, increased production, stronger investment and improved purchasing power deliver measurable benefits to Nigerians. The IMF has projected Nigeria’s real gross domestic product growth at 4.1 per cent in 2026 and 4.3 per cent in 2027.
The institution also emphasised the need for sustained reforms, fiscal discipline and policies that support inclusive economic growth.